
How long you can stay in Spain before you move, how Europe's new border system counts your days, and how you can become a Spanish taxpayer without breaking a single rule.
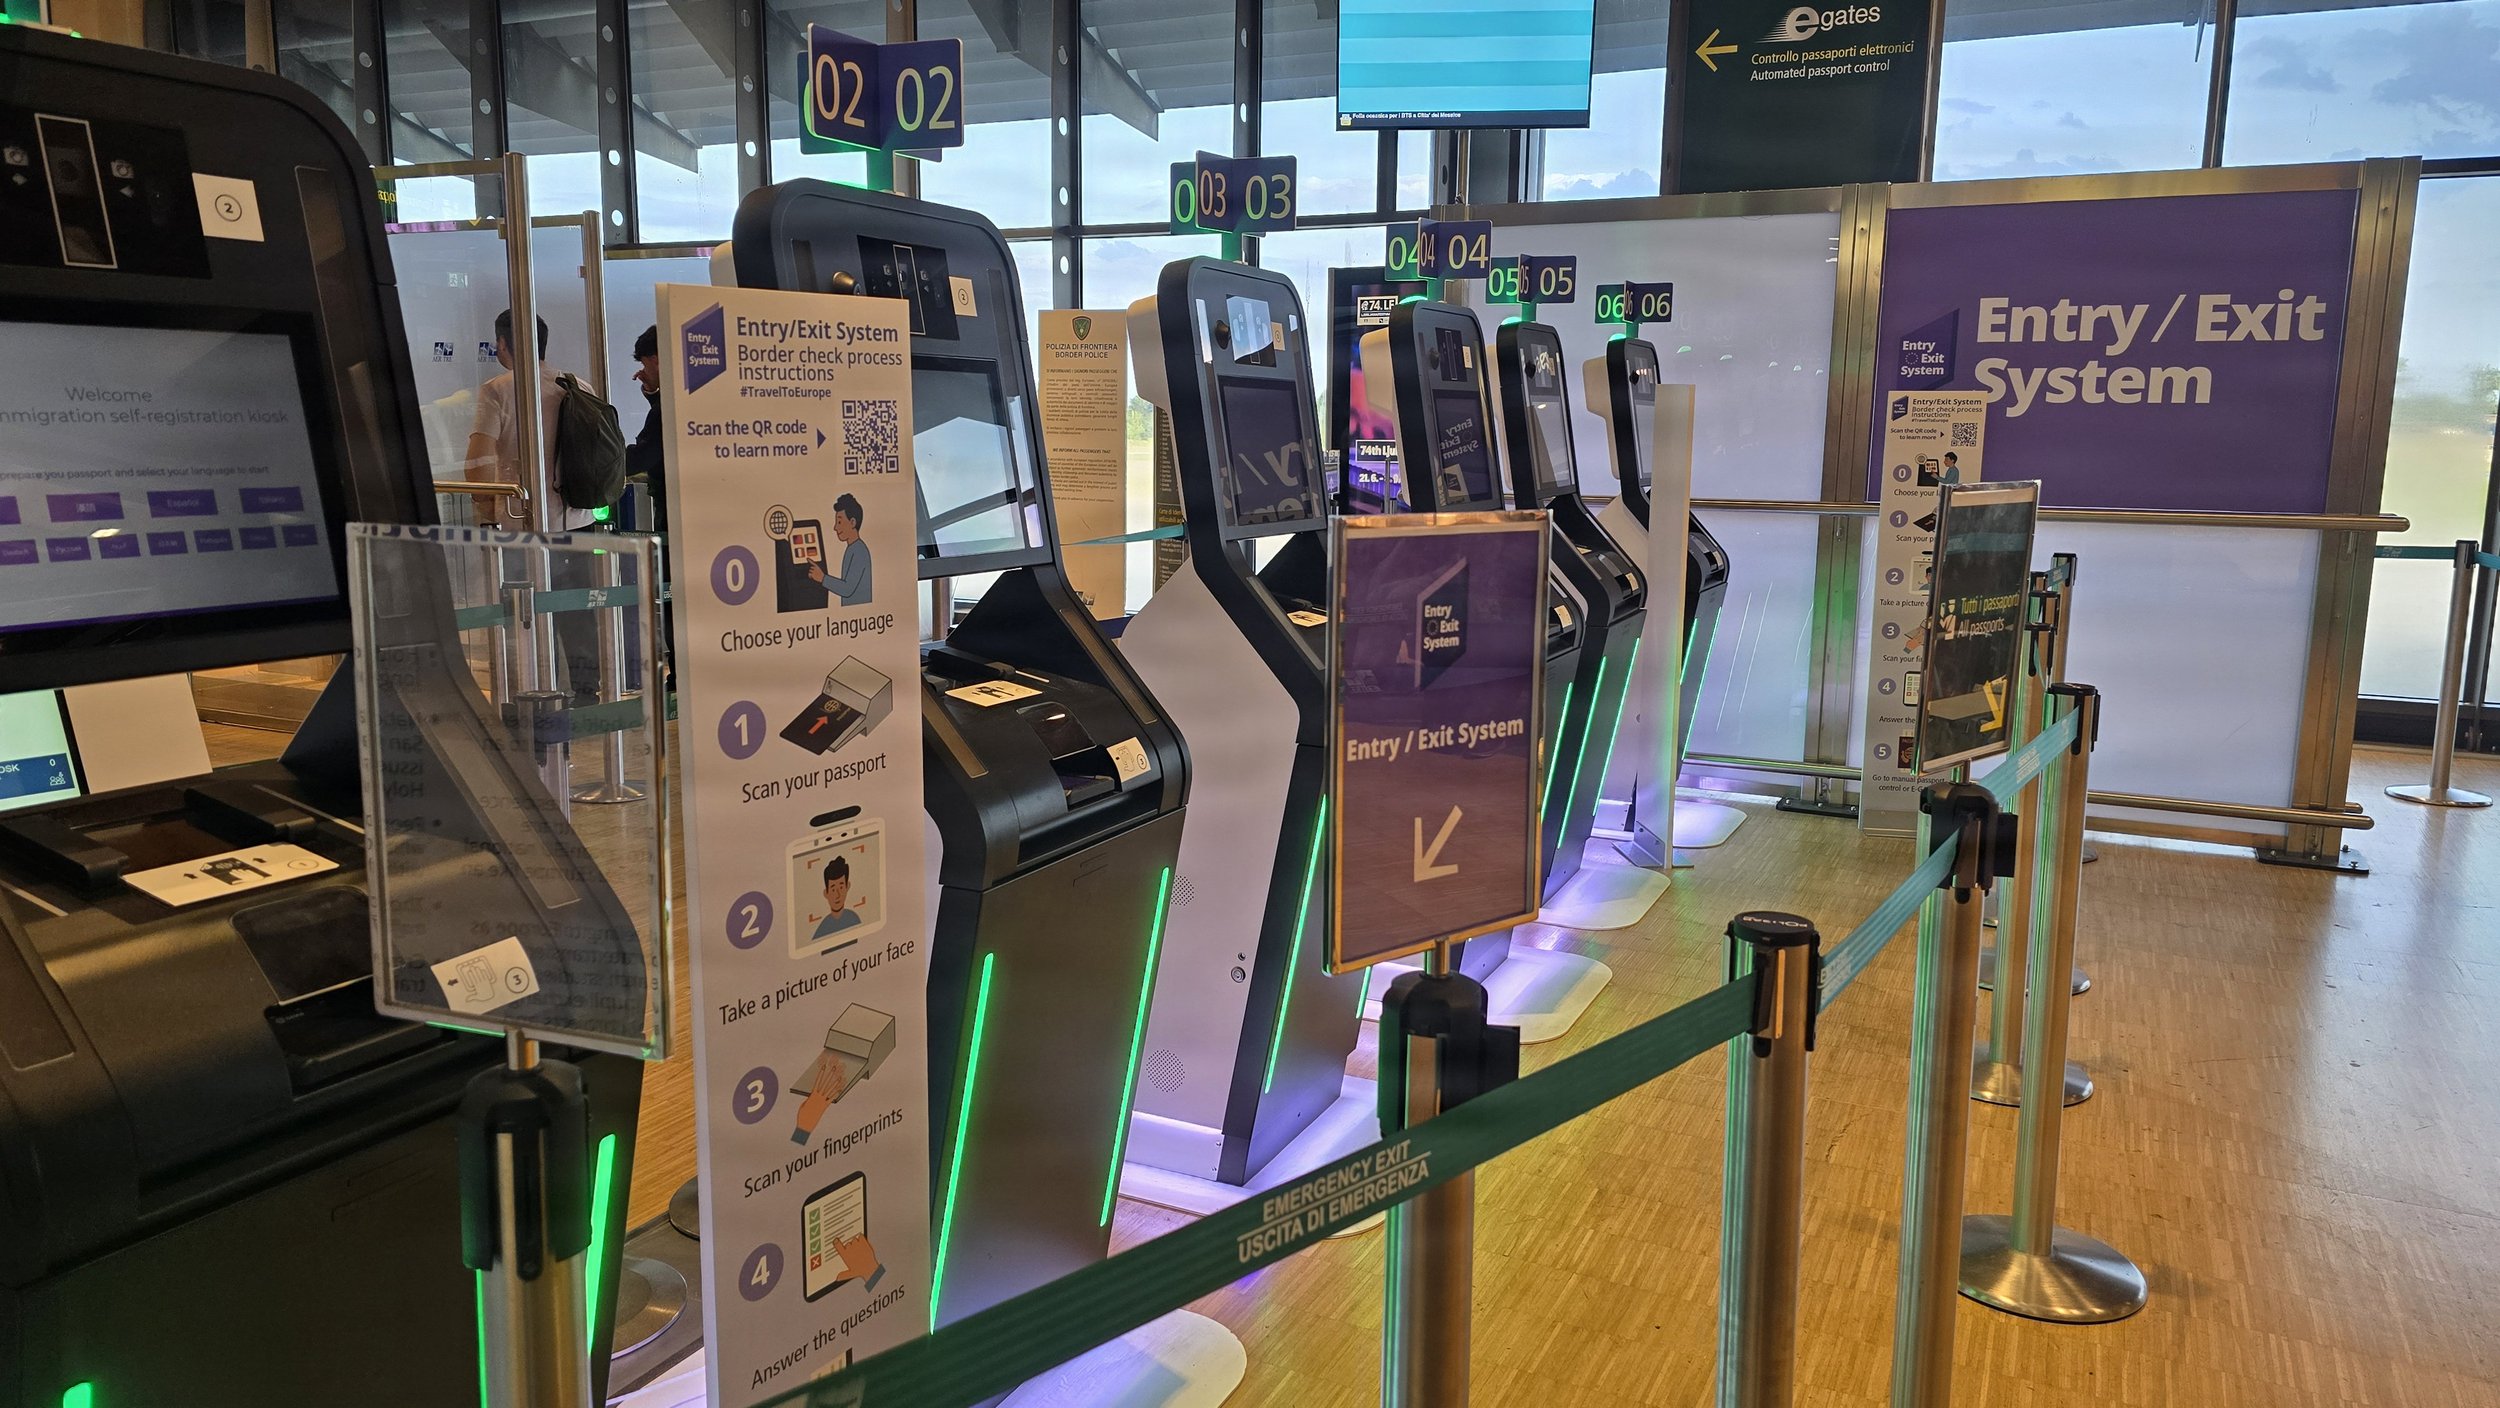
“Entry/Exit System kiosks now record every non-EU visitor’s entry and exit. Photo: Randall Jackson via Wikimedia Commons (Public Domain).”
Introduction
Most people who move to Spain do not arrive in one go. They come for a month in the spring, return in the autumn, look at neighbourhoods and schools, and plan to decide properly next year. Whether they are coming from New York, London, Toronto or Dubai, on a US, UK or Canadian passport, that feels like visiting, and in immigration terms it is.
In tax terms it may not be. Two different rules decide how long you can stay and whether Spain can tax you, and they count your days in different ways. It is possible to follow the immigration rule exactly and still become a Spanish tax resident for a whole year, without ever having intended to move. Since April 2026, every one of those days has been recorded.
The stamp has gone. The count has not
If you have flown into Europe recently, you may have noticed that nobody stamped your passport. The stamp has been replaced by the Entry/Exit System, known as EES. It records every entry and exit by non-EU visitors on short stays in the 29 European countries that use it, including Spain. Instead of ink, it stores your fingerprints, a photograph of your face, your passport details, and the date and place you entered or left.
The rollout began in October 2025, and the system has been running at every external border since 10 April 2026. By the end of March 2026 it had recorded more than 45 million crossings and refused entry to over 24,000 people. Your record is kept for three years, or five if there is no record of you leaving.
EES applies only to short-stay visitors. Once you hold a Spanish residence card or a long-stay visa, you are not registered in it, and your days in Spain as a resident do not count towards the 90-day limit. This includes British nationals who were living in Spain before 2021 and hold a Withdrawal Agreement residence card. Those days still count for tax.
Registering for the first time takes a few minutes, and later visits are quicker. Queues have been the main complaint: airports and airlines reported waits of up to two hours in early 2026 and warned of four hours or more in the summer. A separate travel authorisation, ETIAS, is expected from the last quarter of 2026. It will cost €20 (free for under-18s and over-70s) and last three years.
The 90/180-day rule
US, UK and Canadian citizens, and most other visitors who do not need a visa, can spend up to 90 days in any 180-day period in the Schengen Area.
The 180 days are not a fixed half-year. On any given day, count back 180 days and add up every day you spent anywhere in the Schengen Area. A week in Paris and a long weekend in Rome come out of the same 90 days as your time in Spain. There is no separate allowance for each country.
The day you arrive and the day you leave both count as full days. The EU publishes an official calculator, linked at the end of this article, that shows how many days you have left.
In Spain, overstaying is a serious immigration offence. The normal consequence is removal from Spain with a ban on entering the Schengen Area, typically for up to five years; a fine of €501 to €10,000 applies only in limited cases. Other Schengen countries apply their own penalties. Before EES, overstays were hard to detect. They are now flagged automatically, and a recorded overstay will come up again in any later visa or residence application.
The rule at a glance
Up to 90 days in any 180-day period, across all Schengen countries combined.
Count back 180 days from any date. It is a rolling window, not a fixed half-year.
Arrival and departure days both count, and part of a day counts as a full day.
In Spain, overstaying normally means removal and an entry ban of up to five years.
Days spent in Spain as a resident do not count towards the 90, but they do count for tax.
Where 90/180 meets the 183-day rule
Spain treats you as tax resident for a calendar year if you spend more than 183 days in the country between 1 January and 31 December. The days do not need to be consecutive. "More than 183" means that 184 days is the trigger.
Now put the two rules side by side. Someone who spends 1 January to 31 March in Spain, leaves, returns from 30 June to 27 September, and comes back for the last five days of December has never broken the 90/180 rule. They have also spent 185 days in Spain that year. That makes them a Spanish tax resident, and because Spain does not split the tax year, they are resident from 1 January, not from the day they crossed the line.
Short trips out of the country do not necessarily reset the count. Spain can treat a week in London or a long weekend in Lisbon as part of your time in Spain, unless you can show you are tax resident somewhere else with a certificate from that country's tax authority. Spain calls these sporadic absences (ausencias esporádicas).
Days are only one of three tests, and meeting any one of them is enough:
Days: more than 183 days in Spain in the calendar year.
Economic interests: Spain is where your main business or the main base of your income and assets is, however few days you spend here.
Family: your spouse (unless legally separated) and your children under 18 live in Spain. You are then presumed resident unless you can prove otherwise. This catches people whose family moves first while they keep working abroad.
What becoming resident means
A Spanish tax resident pays Spanish income tax on their income from everywhere in the world: salary, bonuses and share awards, rent from a property at home, dividends, interest and gains, and pensions. Rates on earned income start at about 19% (18% in Madrid) and reach 45% in Madrid, 50% in Catalonia and about 54% in the Valencia region at the top. Investment income is taxed separately, at 19% to 30%. Foreign assets worth more than €50,000 in each category must be declared each year on a form called Modelo 720, and some regions charge wealth tax.
Where Spain and your home country both treat you as resident, the tax treaty between them decides which country has first claim, and tax paid in one is usually credited against the other. The planning steps that make the biggest difference, such as when a business or property is sold, how investments are held, and whether you qualify for the Beckham Law, mostly have to be taken before Spanish residence starts. That is why accidental residence is expensive, and planned residence usually is not.
If you are American. The US taxes its citizens wherever they live, and FBAR and FATCA reporting continue, so Spanish tax comes in addition to US tax, not instead of it. The US gives credit only for tax actually paid to Spain, so a lower Spanish bill can mean a higher US one. Spain also does not follow US treatment of retirement accounts. It has no equivalent of a Roth IRA, and how withdrawals from a 401(k), a traditional IRA or a Roth are taxed depends on the account and on when you become resident.
If you are British. The UK applies its own residence test, and becoming Spanish resident does not automatically end UK residence. The UK has no exit tax, but if you return within five years, gains you made abroad on assets you owned before leaving can become taxable in the UK. Spain does not recognise ISAs, so the income and gains inside them become taxable in Spain once you are resident.
If you are Canadian. Canada decides residence by your ties to the country rather than by days alone. When you leave, it generally treats your assets as sold at their market value and taxes the gain, with exceptions that include Canadian real estate and RRSPs.
If you live somewhere with no income tax, such as the UAE. The change is larger, because income that is untaxed today becomes taxable in Spain from the first day of the year you become resident. The date you arrive matters even more.
If you own property in Spain but do not live here, you pay Spain's non-resident income tax instead. Collections have grown quickly, mainly from property sales and capital gains:
| Non-resident income tax collected | 2023 | 2024 | 2025 |
|---|---|---|---|
| Amount collected | about €3.2bn | €4.04bn | €5.40bn |
| Growth on previous year | +8.9% | +25.4% | +33.8% |
Source: Agencia Tributaria, annual tax revenue reports. The 2025 figure includes a one-off assessment of €331 million.
The order to do things in
What we have seen most often is the same sequence: find the area, look at houses, come and go for a year, and speak to a tax adviser once the move is under way. By then, some of the useful decisions have already been made by default.
The order we work in is this.
Count your days and fix a residence date. Decide which calendar year you want to become resident in, and plan your visits so that you do not become resident earlier by accident. If you are selling a business or a property, decide whether the sale happens before or after that date, because it can change which country taxes the gain.
Map your tax position before you apply for anything. Your income, your investments and pension accounts, any business interests, and whether you qualify for the Beckham Law, modelled year by year under each option, alongside the position in your home country.
Choose the visa that fits the tax plan. If you work remotely for an employer or clients outside Spain, that is usually the Digital Nomad Visa. In 2026 it requires an income of about €2,850 a month from outside Spain, plus an amount for each family member, and it can lead to long-term residence after five years. If you live on pensions or investments, it is usually the Non-Lucrative Visa, at about €2,400 a month plus €600 for each family member. It does not allow you to work in Spain. If you are moving for a job with a Spanish employer, or to run a company here, the route is a work permit or the entrepreneur route, and the timing of the contract matters for the Beckham Law.
Arrive, register, and then buy. Rent first. Register with Social Security when the plan says to, and file for the Beckham Law within six months. Buy once the regime is secured and the region is confirmed.
The Beckham Law is the reason the order matters so much. If you move to Spain to work and have not been a Spanish tax resident in the previous five years, it taxes your employment income at a flat 24% up to €600,000 a year (47% above that), wherever the work is done, and your foreign investment income is not taxed in Spain at all. It lasts for the year you become resident and the following five. Employees working remotely for a foreign employer can qualify; the self-employed generally cannot. The application must be made within six months of the start date on your Social Security registration, and there is no extension. For Americans, foreign investment income that Spain does not tax under the Beckham Law is still taxed in full in the US, so the planning is greater, not less. Our article on the Beckham Law explains how it works in more detail.
Reading this and unsure where you stand? The Spain readiness quiz takes a couple of minutes and shows which of these steps you have covered and which still need attention.
“The point of the planning is to enjoy Spain.”
How we work
IPTW handles immigration, tax and property as one decision, because the order you take them in is usually worth more than any one of them. Most of our clients arrive with a competent accountant at home and a lawyer in Spain, and neither of them is looking at the gap between the two systems. That gap is where we work.
We do not manage money or sell financial products, so there is nothing we are steering you towards. The people you speak to are the people who do the work. If your situation is simple, we will tell you so.
The first conversation is free.
Book a free first conversation →
Download this article as a PDF
To read offline or print download the PDF.
Useful links
EU official short-stay Schengen calculator (European Commission)
Frequently asked questions about the Entry/Exit System (EES) (Travel Europe)
IPTW tax calculator: estimate your Spanish tax, with and without the Beckham Law
This article is general information only and is not tax or legal advice. Individual circumstances vary, so take advice before acting. Figures current at November 2026.
